Picture a small direct-to-consumer brand with a good year behind it. Orders doubled, reviews are strong, the founders are tired and pleased. Then the marketplace holds back a settlement for three weeks, a supplier asks for advance payment on the next batch, and the bank balance that looked comfortable on Monday can’t cover salaries on Friday.
That’s an invented example, but founders will recognise it. Money trouble in a young company rarely arrives as one big failure. It builds up through timing gaps that nobody was watching. Anyone who follows the ecosystem through Malik Times Startup News will see the same pattern in the stories of companies that stall: the idea was fine, the cash planning wasn’t.
Note: Please keep in mind that the “schemes”, “tax rules” and “compliance dates” changes often, so it’s better to verify anything below with the official source or your accountant before acting.
Choosing money that suits your stage
Every kind of funding costs something, and interest is only part of it.
Savings and early customers are the first source. It’s slow, but nobody else has a say in your decisions, and you learn very quickly which spending actually produces sales.
Angel investors come next for many teams. They’re individuals writing cheques from their own pockets, often before there’s much revenue. The most helpful ones offer more than money. They might connect you with a “distributor” or tell you honestly what they think of your pricing.
Seed rounds and venture capital suit companies with a working product and proof that people want it. Know what the VC wants before signing the deal. VCs make most of their returns from a few big wins, so they may push you to grow quickly, even if taking things slowly makes more sense for your business.
If your market is big enough to build a very large company, that’s a fair trade. If you’re aiming for a healthy, profitable business of moderate size, venture money can pull you somewhere you didn’t want to go.
Debt works for businesses with predictable income. Bank loans and venture debt leave your ownership untouched, but the instalments don’t care how the month went. Government support is the option people skip: with DPIIT recognition you can apply to schemes such as the Startup India Seed Fund Scheme, which operates through approved incubators. Expect forms and waiting, but usually no equity given up.
Before settling on an amount, see how much similar companies have raised. The Malik Times Funding Tracker shows recent funding rounds and the investors involved. It can give you a clearer idea of what to expect than a figure you heard at a meetup.
A budget short enough to read
Most startup budgets fail because they’re too detailed to maintain. One page is enough.
Rent, salaries, software and loan payments don’t stop just because sales have dropped. You can cut back on ads, travel and materials. Try not to take on more fixed costs than the business can handle.
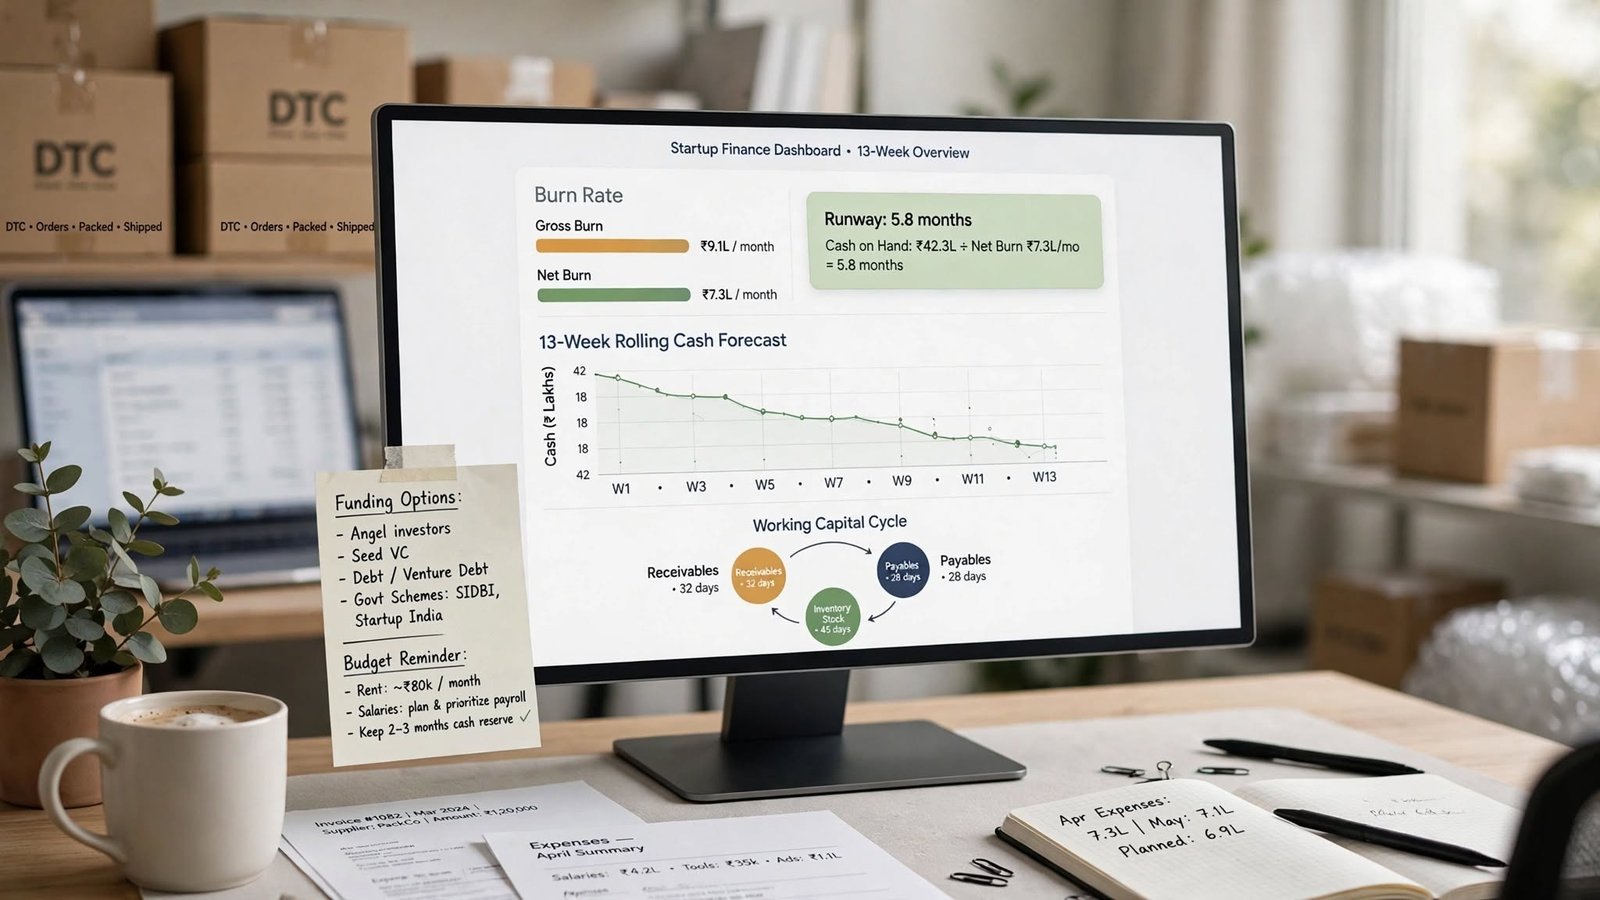
Add working capital to the picture. That’s the money locked up in operations: what customers haven’t paid yet, stock sitting in a warehouse, less what you owe suppliers and staff soon. If you pay suppliers within “30 days” but wait “75 days” for customers to pay, your money stays stuck for “45 days”. The more you sell, the more money you may need to keep the “business” running.
Forecast revenue twice, once hopefully and once cautiously. Plan your spending against the cautious one. Then add a reserve line for the unexpected: a regulatory notice, a price rise from your main supplier, a client who vanishes. Two to three months of fixed costs is a sensible cushion.
Runway, with real numbers
Profit and cash are different animals. A company can show profit on paper and still miss payroll because customers pay late. Salaries are paid in cash.
Gross burn is everything you spend in a month. Net burn is that minus what comes in from customers. Runway is the cash you have divided by net burn.
Take a startup with ₹2.4 crore in the bank, monthly spending of ₹32 lakh and collections of ₹14 lakh. Net burn is ₹18 lakh, so runway is about 13 months. Now stress it. The biggest client delays payment by two months and a seasonal dip cuts sales by a fifth. Suddenly net burn is nearer ₹26 lakh and runway is nine months. That’s a different company, with a different set of decisions, and you found out from a spreadsheet instead of a bounced salary.
For the short term, keep a rolling forecast of the next 13 weeks: every expected receipt and payment, week by week, refreshed on a set day. It sounds fussy. It’s also the earliest warning system a small company can afford.
Collections deserve their own routine. Large Indian customers often take 60 to 90 days to pay, while your team expects salary on the last working day. Send invoices the day work is delivered. Ask new clients for an advance or milestone billing. Follow up on a calendar, not when you’re desperate. And if you’re registered as a micro or small enterprise, ask your CA about Section 43B(h) of the Income Tax Act, which ties a buyer’s tax deduction to timely payment of dues to such suppliers. It can give you a legitimate reason to nudge a slow payer.
Preparing to pitch
Investors may ask about your “monthly revenue”, as well as growth, customer acquisition cost, churn or gross margin. Be familiar with these “numbers” so you don’t have to dig through spreadsheets when someone asks how the business is doing.
Say exactly what the money is for. “Expansion and hiring” means nothing. “Two engineers, a sales lead and 15 months of runway to reach ₹10 crore in annual revenue” can be judged.
On valuation, remember there’s no formula for a business with thin revenue. At seed, founders commonly give up roughly 15 to 25 percent, though it varies. Terms matter as much as price: a heavy liquidation preference can cost you more two rounds later than a few extra lakhs of valuation gained today. And an inflated valuation sets a bar you then have to clear, or the next round comes in lower.
Start before you’re desperate. A raise often takes three to six months from first conversation to money received. Begin with “nine months” of runway and you can decline an unfair offer. Keep your “incorporation papers”, cap table, contracts and financial records together from the start. When investors ask for them, you should be able to share everything without wasting time looking for documents.
Tools that keep you honest
You don’t need an expensive finance stack. You need something that shows reality quickly.
Accounting software linked to your “bank account” cuts manual entry and the errors that come with it. Plus, you should “automate invoice” reminders and recurring payments.
AI tools can also help you make sense of your accounts. They may point out customers who pay late, products that aren’t making money or costs that keep rising. But they don’t always get it right, so it’s better to “check the figures” yourself before making any decisions based on what they tell you. And find out where customer data goes before you paste it into anything. The “India’s Digital Personal Data Protection Act, 2023” places duties on businesses that handle personal data, so take legal advice on how it applies to you.
Mistakes worth avoiding
Treating a fresh round like income is the common one. It’s a countdown, and hiring or renting as though it were revenue shortens that countdown.
Watching only revenue and profit is another. Check cash every week.
Messy books cost a lot later. When personal and business expenses get mixed up, invoices go missing or accounts aren’t checked regularly, problems tend to show up during a tax review or investor checks. Sorting them out at that stage can cost a lot.
Scaling before the unit economics work does the most damage, because it looks like success. If winning a customer costs “₹800” and that customer spends “₹600” once, growing faster only makes the loss larger. Know your acquisition cost, margin and payback period first.
Smaller slips add up too: forgetting GST, TDS and PF filings that fall due regardless of how the month went, raising so much that spending turns sloppy, or raising so little that you’re back at investors’ doors within nine months.
Growth you can sustain
The best growth plan I can offer is unglamorous: last long enough to find out what works.
Losing money while you search for your market is fine, but give every customer segment a date by which it should pay for itself. Tie hiring to a goal for the next “12 to 18 months”, such as a “revenue figure” or a launch, and let roles that don’t serve it wait a quarter.
Pick your trigger now, while things are calm. When runway drops below nine months, you either start raising or start cutting. When you make that decision in advance, it will keep panic from making it for you.
Expand only when the first market works. Opening in several cities before one is profitable is how plenty of rounds disappear.
See also: 5 Ways to Pay for Unexpected Medical Bills
Frequently asked questions
How do startups manage cash flow?
To manage cash flow, they should forecasting weekly, checking “burn” and “runway” monthly, invoicing promptly, chasing late payments and keeping a reserve.
How much runway should a startup have?
After a raise, “12 to 18 months” is a common target, and many advisors suggest starting the next round while six to nine months remain.
Which funding is best for an early-stage Indian startup?
It depends on stage. Many begin with savings or an “angel investor”, then move to seed or venture funding once there’s a working product and early customers.
What’s the difference between profit and cash flow?
Profit is revenue minus costs on paper. Cash flow is the actual timing of money entering and leaving your account.
Final thoughts
In short, “funding” gets the headlines, but cash flow decides who’s still trading next year. Know your runway, keep clean records, raise from people who suit your business and spend against milestones.